If your commercial property insurance claim was denied in California, start by reviewing the denial letter, your policy’s coverage terms and the deadline to sue. Depending on the dispute, you may challenge the denial with additional evidence, request appraisal for a disagreement over the amount of loss, or pursue legal action. A commercial insurance claims lawyer at Viciti Law can help you understand which options apply.
What Should You Do First After a Commercial Property Claim Denial?
First, get the denial in writing with every reason, a complete copy of your policy, and the insurer’s claim documents. Next, find your deadline to sue, which is often stated in the policy’s suit clause. Then choose how to challenge the decision. The right path depends on whether the dispute is about coverage, the amount, or both.
If your commercial policy includes fire coverage, Insurance Code section 2071 lets you request claim-related documents. The insurer must send copies within 15 calendar days of your request. These include estimates, scopes of loss, appraisals and reports on the amount of loss.
A commercial insurance claims lawyer can make these requests for you. Meanwhile, write down the date and substance of every conversation with the adjuster, and keep copies of everything you send.
Why are commercial property claims denied?
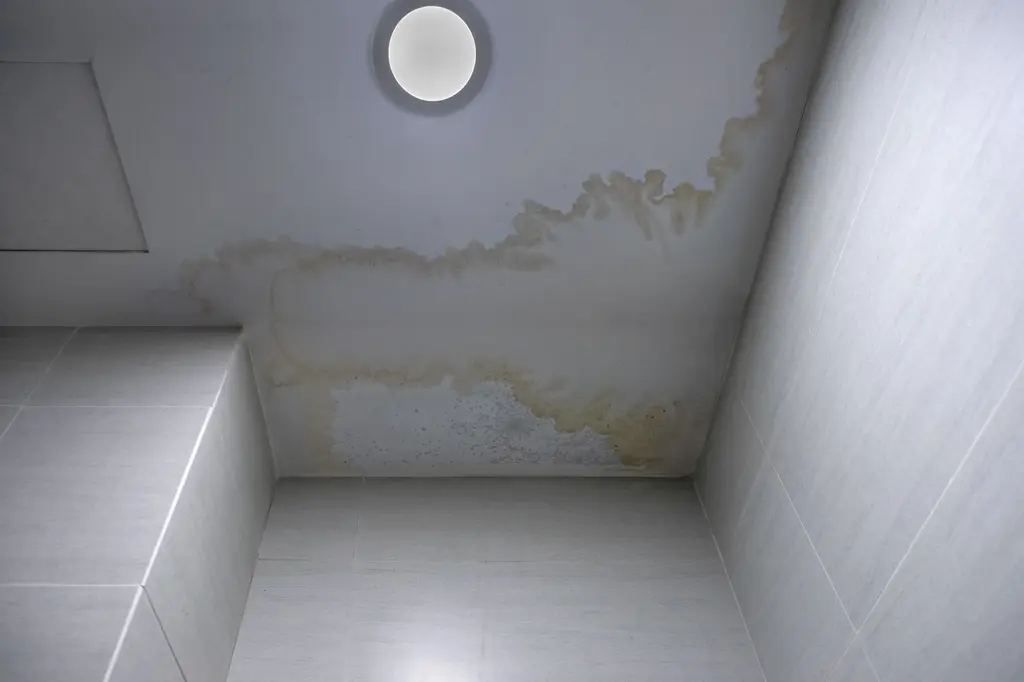
Insurers deny commercial property claims for many reasons: exclusions, disputes over cause, late notice and missing records. Some denials follow the policy correctly. Others rest on a reading of the policy, or of the facts, that you can challenge with better evidence. The denial letter should tell you which reason the insurer relied on.
Common grounds include:
- Exclusions, such as wear and tear, gradual leaks, mold or flood, depending on the policy
- Disputes over cause, for example a sudden pipe burst versus a slow leak
- Vacancy clauses that limit coverage when a building sits empty for a set period
- Missed conditions, such as a sworn proof of loss or an examination under oath
- Business interruption figures that do not clearly show the lost income
Late notice, another common reason, does not automatically defeat a claim. Under a long-standing California Supreme Court rule, an insurer relying on late notice generally must prove the delay substantially prejudiced it.
What must your insurer do under California rules?
California’s Fair Claims Settlement Practices Regulations set firm timelines for business claims as well as personal ones. Your insurer has 15 calendar days to acknowledge a notice of claim. After it receives proof of claim, it has 40 calendar days to accept or deny. Any denial has to be written and must list all of its grounds.
The Fair Claims Settlement Practices Regulations also cover business interruption claims, and the Department of Insurance has reminded insurers of that. If the insurer needs more time, it must say so in writing, explain what it still needs, and send an update every 30 days. A written denial must also tell you that you can ask the department to review it.
Insurance Code section 790.03 adds a list of unfair claims practices. Examples include misstating policy terms, failing to respond reasonably promptly, and failing to explain a denial or a low offer. The Insurance Commissioner enforces these standards.
How do business interruption claims work, and why are they disputed?
Business interruption coverage, often called business income coverage, may replace income a business loses while covered property damage keeps it closed or slowed. Coverage usually lasts for a period of restoration that the policy defines. Disputes tend to center on how long that period should run and how much the business would have earned.
To support your claim for lost income, gather records showing what the business likely would have earned. Insurers commonly ask for:
- Tax returns and profit and loss statements from prior years
- Monthly sales, payroll and bank records
- Leases, loan payments and other expenses that continued during the closure
- Repair schedules and contractor timelines
Some policies also include extra expense coverage for reasonable costs to keep operating, such as renting a temporary space. Policy wording varies, so read the definitions and time limits closely. A commercial insurance claims lawyer may also work with an accountant to test the insurer’s numbers.
How Can You Challenge a Commercial Insurance Claim Denial in California?
You can answer the denial in writing with new evidence. If the dispute is about the amount of loss, appraisal may help. You can also complain to the California Department of Insurance or sue for breach of contract and bad faith. The right mix depends on why the insurer said no.
- Written response: answer each reason in the denial with documents, photos and outside reports, then ask the insurer to reconsider.
- Appraisal: a process in fire policies that sets the value and amount of loss (see the FAQ below).
- Department of Insurance complaint: call 1-800-927-4357 or file online. Its review is separate from any lawsuit, and your deadline to sue still applies.
- Lawsuit: a breach of contract claim seeks the benefits the policy owes. If the denial was also unreasonable, it may support a claim for insurance bad faith.
When should a business owner call a commercial insurance claims lawyer?
Call a commercial insurance claims lawyer when the insurer’s reasons conflict with your policy wording or your records. The same goes for missed insurer deadlines or a substantial difference between your lost-income calculation and the insurer’s estimate. Also call well before your deadline to sue, because the policy’s suit clause can cut off the claim.
Other signs include repeated requests for the same documents, a reservation of rights letter, or a scheduled examination under oath. For a broader look at timing, read about when to hire a lawyer to fight an insurance company.
Viciti Law handles commercial property insurance claims for owners of shops, restaurants, offices and rental buildings across Southern California.
Frequently Asked Questions
Can I get a copy of my full policy from the insurer?
Yes, if your policy falls under Insurance Code section 2071, which governs fire policies. After a covered loss, section 2084 requires the insurer to send a free, complete copy of the policy in effect at the time of the loss. The deadline is 30 calendar days from your request. The copy must include endorsements and the declarations page. Even without a loss, you may request one free copy each year.
What is appraisal in a commercial claim?
Appraisal is a way to settle a disagreement over the value of property or the amount of a loss without a trial. Each side picks an appraiser, and the two appraisers choose an umpire. Then a written award signed by any two of the three sets the amount. Appraisal does not decide whether a loss is covered, so it fits disputes about numbers.
Does Bad Faith Apply to Business Insurance Policies in California?
Yes. The duty of good faith and fair dealing is part of commercial property and business interruption policies, not only homeowners coverage. If an insurer unreasonably withholds benefits the policy owes a business, the business may have a bad faith claim alongside its contract claim. For the warning signs, see what counts as a bad faith claim.
How Long Do I Have to Sue My Commercial Insurance Company in California?
Start with the suit clause in your policy. For fire policies, Insurance Code section 2071 allows at least 12 months from the inception of the loss. When the loss relates to a declared state of emergency, the period is 24 months. Under a 1990 California Supreme Court decision, the clock stops from notice of the loss until the written denial. For a bad faith tort claim, the usual limit is two years (Code of Civil Procedure section 339).
Talk to Viciti Law About a Denied Commercial Claim
If your business insurance claim was denied, delayed or underpaid, contact Viciti Law for a free consultation. A commercial insurance claim lawyer at the firm can review your denial letter, policy and records with you.
Call (310) 919-5011 or visit the office in Sherman Oaks. The firm speaks English, Spanish and Russian, and it takes each and every case personally.
Past results do not guarantee a similar outcome. This article provides general information about California law and is not legal advice. Reading it does not create an attorney-client relationship. Attorney Advertising.
